Do I Need 20% Down to Buy a House in Atlanta?
Often, no. Here are the real down payment minimums and the Atlanta programs that can help cover the rest.
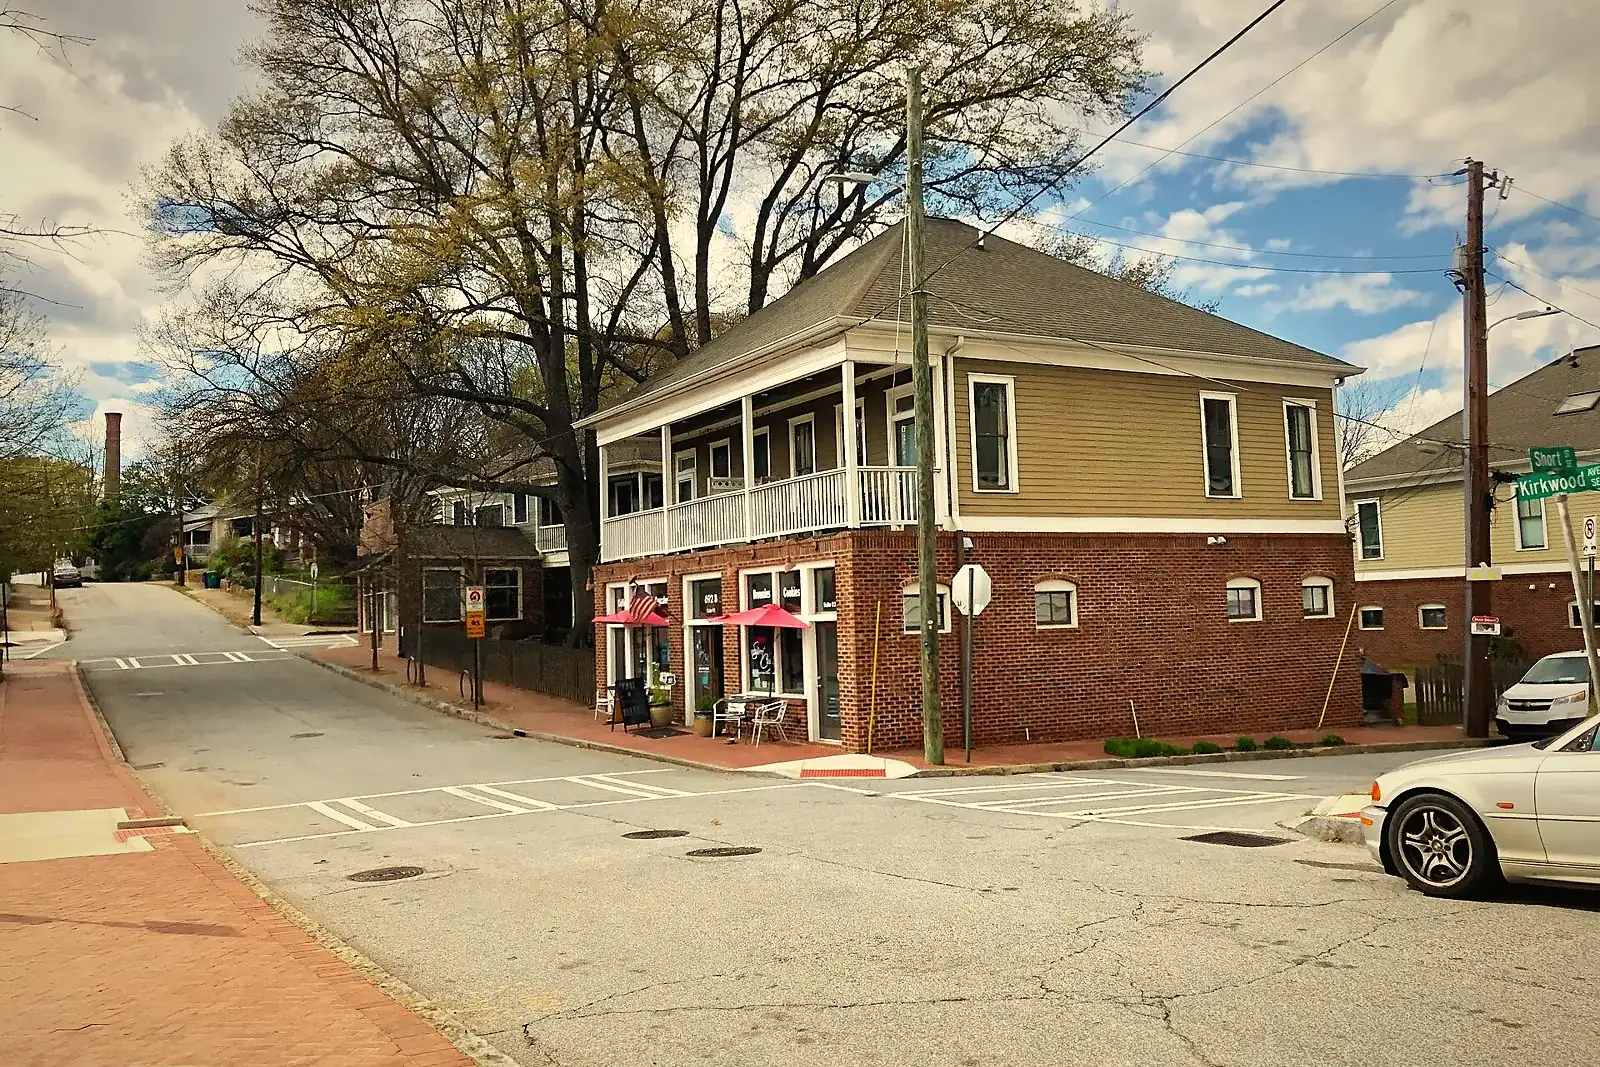
A two-story home on a corner in Cabbagetown. Photo: w_lemay, via Wikimedia Commons (CC0), color adjusted.
If you’ve been saving toward 20% and wondering if you’ll ever get there, you’re in good company. It’s one of the most common questions we hear.
Do I need 20 down to buy a house in Atlanta? Often, no. FHA loans allow as little as 3.5% down, many conventional loans allow 3%, and VA loans may need nothing down. Georgia Dream and Invest Atlanta programs can help cover what’s left. Putting less down usually means paying mortgage insurance.
How much do you really need to put down on a house?
Here are the minimums, from the agencies themselves:
- FHA loans: 3.5% down. HUD sets the minimum investment at 3.5%. A credit score of 580 or higher qualifies for that maximum financing, while scores from 500 to 579 are limited to 90% financing, which means 10% down.
- Conventional loans: as little as 3% down. Fannie Mae offers 97% loan-to-value options with a minimum credit score of 620.
- VA loans: often nothing down. The VA doesn’t require a down payment for eligible service members, veterans and surviving spouses, though lenders may have their own rules.
In real life, most buyers don’t put down 20%. NAR’s 2025 Profile of Home Buyers and Sellers found a median down payment of 10% for first-time buyers and 23% for repeat buyers.
What happens if I put less than 20% down?
You’ll usually pay mortgage insurance. On a conventional loan, it’s called private mortgage insurance, or PMI. The Consumer Financial Protection Bureau explains that PMI protects the lender, not you, if you stop making payments, and it’s typically added to your monthly payment.
Think of it as the cost of buying sooner. For many people, paying PMI for a few years beats waiting years to save 20% while prices and life keep moving. Before you decide, see your full monthly cost with mortgage insurance included.
What down payment help is available in Atlanta?
Two places to start, as of October 2026:
- Georgia Dream (statewide). Up to $10,000, or $12,500 for some buyers, as a 0% loan with no monthly payment, according to the Georgia Department of Community Affairs. Our Georgia Dream walkthrough covers who qualifies.
- Invest Atlanta (City of Atlanta only). ATL HomeNOW offers up to $20,000 for homes inside the city limits, forgiven after 10 years as your primary home, with household income limits starting at $99,000 for one person. Invest Atlanta also runs area programs, like the Vine City Renaissance Initiative at $20,000, forgiven after 5 years.
You can find the down payment programs that fit you in one place.
A quick down payment example
Say you’re buying a $350,000 home in metro Atlanta.
| Down payment | Amount |
|---|---|
| 20% | $70,000 |
| FHA minimum, 3.5% | $12,250 |
| Conventional minimum, 3% | $10,500 |
With $10,000 from Georgia Dream, an FHA buyer’s out-of-pocket down payment could drop to about $2,250, plus closing costs and the program’s own minimum contribution. That’s a very different savings goal than $70,000.
Areas with homes in this range include College Park, covered in our guide to the airport cities south of Atlanta.
Where people get tripped up
Forgetting closing costs. The down payment isn’t the only cash you’ll need. Ask your lender for an estimate early.
Waiting for 20% when it isn’t required. The fix: compare the cost of PMI with the cost of waiting.
Not asking about the house itself. A low down payment works best on a home you’ve checked carefully. Our list of questions to ask before you fall for a house helps.
Questions people ask
3.5% with a credit score of 580 or higher, according to HUD.
Possibly. VA loans may need no down payment, and USDA loans offer 100% financing in eligible rural areas.
No. Invest Atlanta’s programs are for homes within the City of Atlanta limits. Georgia Dream works statewide.
On many conventional loans, you can ask to remove PMI once you reach enough equity. Your lender can explain the rules for your loan.
What this means for you
You don’t need 20% down to buy in Atlanta, and waiting for it could cost you years. Low down payment loans and local assistance can make owning possible sooner, as long as the monthly payment fits your budget. Our step-by-step buyer plan with Julian shows how it all comes together.
Have a question about down payments you’ve been too shy to ask? Send your down payment question to Julian at Ju Sells ATL. There are no silly questions here.
Keep reading more from the Journal
Around Georgia
Best Places to Live in Georgia Outside of Atlanta: Six Towns Worth a Weekend Visit
Six Georgia towns worth a weekend visit, with drive times, median prices and what's new in each.
Atlanta, In Real Life
Johns Creek Just Opened a Brand-New Downtown. Here’s What a Normal Tuesday Looks Like Up North
Johns Creek just opened Medley, its new downtown. Here's daily life up north, with real prices for Johns Creek and Alpharetta.
The Journal
Every story, in one place
Neighborhood guides, Ask Ju answers and building spotlights.
Sources and fact checks (10)
- HUD: What is the minimum down payment requirement for FHA: answers.hud.gov
- HUD: Does FHA require a minimum credit score and how is it determined: answers.hud.gov
- Fannie Mae: FAQs, 97% LTV options: singlefamily.fanniemae.com
- Fannie Mae: You’ve got options when it comes to home financing: yourhome.fanniemae.com
- U.S. Department of Veterans Affairs: VA home loans: www.benefits.va.gov
- NAR: NAR 2025 Profile of Home Buyers and Sellers reveals market extremes (Nov. 4, 2025): www.nar.realtor
- Consumer Financial Protection Bureau: What is private mortgage insurance: www.consumerfinance.gov
- Georgia DCA: Georgia Dream (checked Oct. 30, 2026): dca.georgia.gov
- Invest Atlanta: Homebuyer programs and down payment assistance (checked Oct. 30, 2026): www.investatlanta.com
- USDA Rural Development: Single family housing programs: www.rd.usda.gov
Every figure was checked on the live source page in October 2026. Hero photo: A two-story home on a corner in Cabbagetown. Photo: w_lemay, via Wikimedia Commons (CC0), color adjusted.